Why Do Similar Mycomaterials Perform Differently?
Two mycelium materials can look almost identical yet behave very differently. Their density, strength and water absorption tell a story about the production process behind them. The challenge is learning how to read it.

Stripping the Narrative: Are Mycomaterials Competitive?
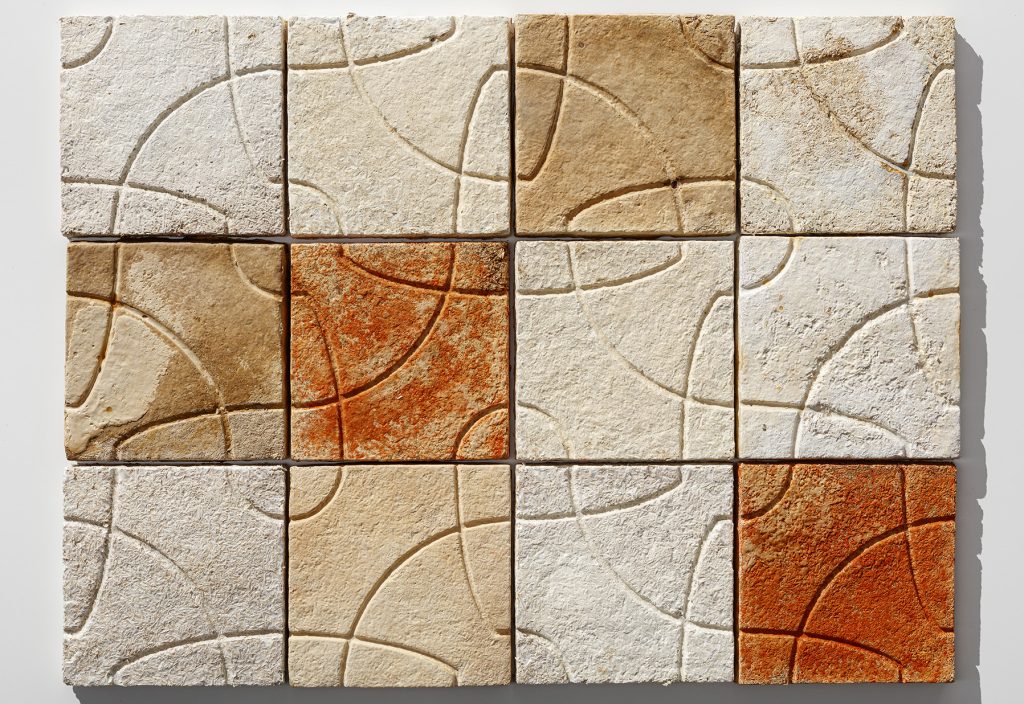
Mycomaterials have a powerful story: biological, circular and seemingly sustainable. But what remains when we strip away the narrative? A critical look at where mycelium-based materials can already compete — and where performance, consistency, cost and scale still set the rules.

Tax information

On-site courses

You pay the Belgium VAT (21%)

You pay the Belgium VAT (21%).

You pay the Belgium VAT (21%).

As a non-resident company within de EU you normally don’t have to pay VAT on purchased goods from another EU member.

But here is an exception, Mycelia Academy has to comply with the new EU regulation on on-site courses. This means, in accordance with Art. 21, §3, 3° WBTW, we have to charge VAT.

In principle, non-resident businesses should be able to recover all, or part of the VAT incurred.

You can find more information on this here.

For more infomation on how you can claim your refund, click here. 

Group consulting / Masterclass

Consumer or company
You pay the Belgium VAT (21%).

Consumer
You pay the Belgium VAT (21%).

Company
If your VAT number is valid on VIES, no VAT is charged.

You are responsible for declaring this purchase in your national VAT return.

This follows the reverse charge rules, where the buyer accounts for the VAT instead of the seller, according to Articles 44 and 196 of the EU VAT Directive 2006/112/EC.

You do not pay VAT.

According to Article 44 of the EU VAT Directive 2006/112/EC, this service is treated as taking place outside Belgium, so no VAT is charged.

Online courses / consulting

Consumer or company
You pay the Belgium VAT (21%).

Consumer
You pay the Belgium VAT (21%).


Company
If your VAT number is valid on VIES, no VAT is charged.

You are responsible for declaring this purchase in your national VAT return.

This follows the reverse charge rules, where the buyer accounts for the VAT instead of the seller, according to Articles 44 and 196 of the EU VAT Directive 2006/112/EC.

You do not pay VAT.

According to Article 44 of the EU VAT Directive 2006/112/EC, this service is treated as taking place outside Belgium, so no VAT is charged.